How to Move from a 457(b) to a Gold IRA in 2026
Are you looking for a way to protect your retirement savings and add more variety to your investments? Moving from a 457(b) plan to a Gold IRA could be an option worth exploring. By investing in physical gold, you can add a different type of asset to your retirement portfolio. But where should you start? First, check your 457(b) plan rules to see if you qualify for a rollover. Next, choose a trusted Gold IRA custodian and open a self-directed IRA. Then, request a direct transfer of your funds and select IRS-approved gold to purchase. This 2026 rollover guide for public sector workers will help you understand each step, avoid common mistakes, and make better decisions for your retirement future.

1. Understanding a 457(b) Plan
A 457(b) is a deferred compensation plan available to state and municipal employees, teachers, law enforcement, and other public service professionals. Contributions are pre-tax, lowering annual taxable income. Funds grow tax-deferred until withdrawal. Unlike a 401(k), workers can access funds without a penalty once they leave service, even if they are under age 59½.
However, growth is tied to traditional financial markets, which means balances may fluctuate sharply during recessions. Many employees with long careers and substantial savings prefer a method that offers more security than market-linked investments alone.
2. What a Gold IRA Offers
A Gold IRA is a self-directed Individual Retirement Account that allows ownership of physical gold and other approved metals. The account is overseen by an IRS-approved custodian and stored in secure vaults. A Gold IRA is popular among those seeking an inflation hedge and a long-term store of value. Precious metals historically maintain purchasing power even during financial instability.
Many public sector workers choose this rollover to diversify beyond stocks and bonds. A Gold IRA is not meant to replace a retirement plan entirely—it complements it with tangible protection.
3. Why Workers Are Choosing to Rollover in 2026
Several motivations stand behind rising interest in rollover planning:
- Growing inflation concerns eroding cash value
- Desire for tangible assets rather than digital account balances
- Concerns over stock market volatility
- Protection of lifetime savings from economic disruption
- Increased awareness of diversification benefits
- Interest in leaving stable assets for heirs
Inflation and global economic tension create urgency around wealth preservation. Preparing in advance gives workers the ability to navigate retirement without relying solely on government market exposure.
4. Eligibility Checklist for a 457(b) to Gold IRA Rollover
Before initiating the transition, confirm the following:
- Separation from employer unless the plan allows in-service transfers
- Access to a self-directed IRA that accepts precious metals
- Metals selected must meet IRS purity rules (99.5% minimum for gold)
- Storage must be completed through an IRS-approved depository
Improper handling may trigger taxes, so following proper procedure is essential.
5. Step-By-Step 2026 Rollover Guide for Public Sector Workers
Step 1: Choose a Gold IRA Custodian
Select a custodian specializing in precious metals. Compare fees, storage partners, customer service, and transparency. Choosing a reputable administrator protects your transfer from costly errors.
Step 2: Open a Self-Directed Gold IRA
Complete account setup and verify identity details. Ensure the account explicitly supports physical metals, not only paper-based gold assets like ETFs.
Step 3: Request a Direct Rollover
Contact your 457(b) plan administrator and request a trustee-to-trustee transfer. In a direct rollover, money moves without you taking possession—avoiding unnecessary taxes and penalties.
Step 4: Allocate Funds to Gold
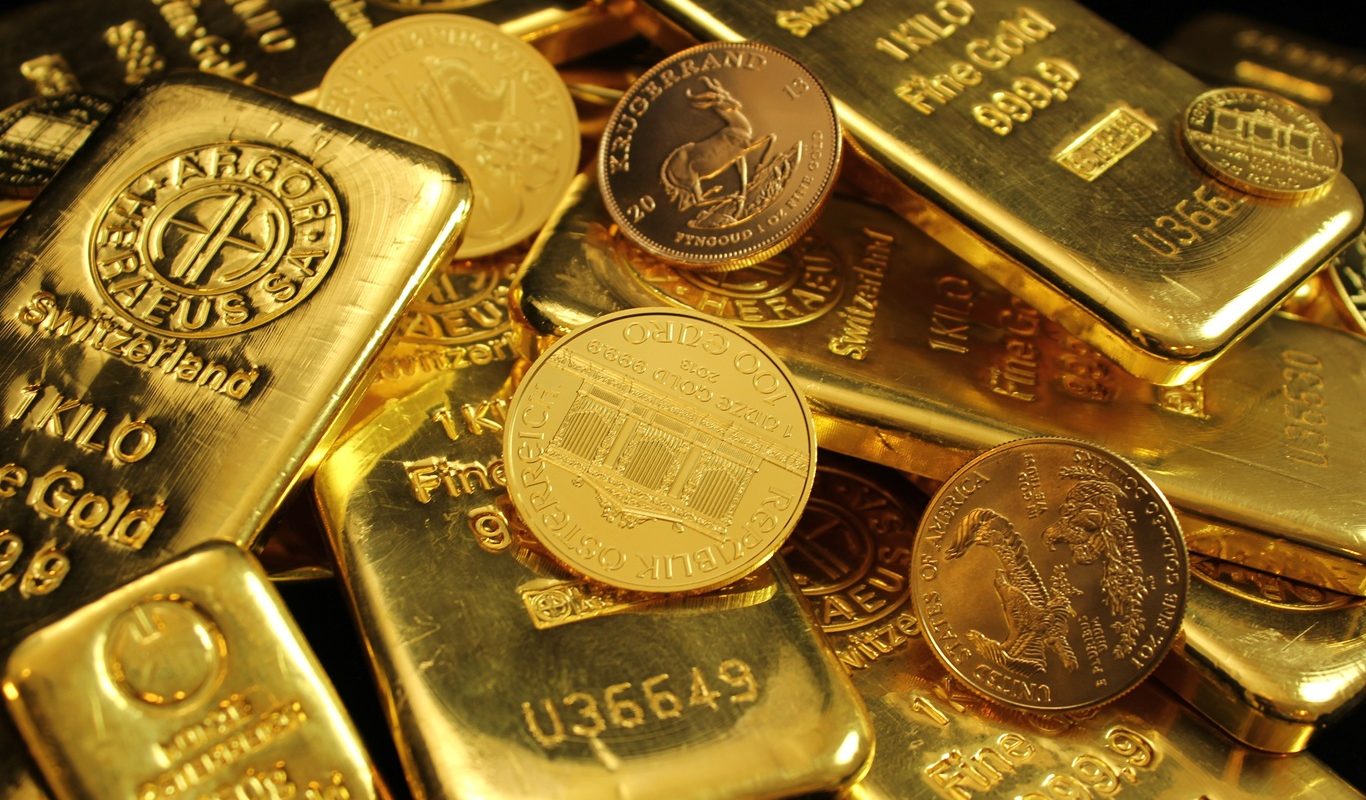
Once funds arrive, you select the type of gold to purchase. Common eligible choices include bullion bars and coins such as American Gold Eagles or Canadian Maple Leafs.
Step 5: Secure Storage
Your gold must remain in a licensed depository. This ensures custody compliance and protection from theft or damage. Home storage does not qualify under federal rules.
6. Direct Rollover vs. Indirect Rollover
1. Direct Rollover – Funds move directly between institutions.
- No tax withholding
- No penalties
- Seamless process
2. Indirect Rollover – Funds pass through your hands first.
- Must be deposited within 60 days
- Subject to mandatory withholding
- Mistakes may trigger taxable income
A direct rollover is almost always the safer option for retirement transfers.
7. Tax Considerations
If done correctly through a direct method, the rollover carries no immediate tax. The assets continue to grow tax-deferred inside the IRA. Taxes apply only when withdrawals occur later in retirement. Workers must also prepare for Required Minimum Distributions once age requirements apply. These RMDs can be taken as gold or converted to cash.
8. Recommended Allocation Approach
Diversification inside a Gold IRA can be structured thoughtfully:
- Gold for long-term wealth protection
- Silver for industrial demand growth
- Platinum or palladium for potential appreciation
A balanced spread creates both security and opportunity. The goal is not speculation—it is preservation.
9. Why 2026 Is an Ideal Planning Window
The upcoming economic cycle highlights long-term uncertainty. Public pensions remain sensitive to interest rates and market returns. Converting part of a 457(b) to gold strengthens retirement stability before financial instability grows more severe. Planning early means protection later. Precious metals have stood against centuries of currency failures and recessions. They serve as a pillar for retirement assets that must endure for decades.
Moving from a 457(b) to a Gold IRA in 2026 can help you add gold to your retirement savings. First, check your plan rules, choose a trusted Gold IRA company, and arrange a direct transfer. Learn how to transfer 457b to Gold IRA rollover without penalty to avoid extra taxes and make the process easier.
This 2026 rollover guide for public sector workers provides a simplified and practical path for transitioning from a 457(b) into a Gold IRA. With the right custodian selection, direct transfer method, and balanced allocation of metals, public employees can secure their retirement with confidence. The future demands preparation, not assumption. A well-executed rollover offers the strength of physical assets that retain value amid uncertainty. Long-term security is achievable. It begins with informed action.






Leave a Comment